Circana: Europe’s €361 Billion Foodservice Market Masks Sharp Generational Shifts
Europe’s foodservice market appears stable on the surface, but beneath the headline figures consumer behaviour is changing rapidly by generation, according to new analysis from market research firm Circana.
Presenting at the European Foodservice Summit in Madrid on 21 September, Edurne Uranga, Circana’s vice president for foodservice in Europe, described the current environment as a “deceptive calm”.
The headline picture
Across the five largest European markets, Great Britain, Germany, France, Spain and Italy, foodservice spend rose 1.4% in the year to June 2026, taking the total to €361.2 billion. Visits declined 0.7%, while the average eater check increased 2.1%.
Uranga argued that age alone is no longer a reliable guide to behaviour, with technology, health, economic pressure and life stage all shaping choices, and that tomorrow’s consumers will not simply behave like younger versions of today’s older diners.
Younger generations punch above their weight
Population share proves a poor predictor of foodservice relevance. Gen Z represents 16% of the population across the five markets but makes 39% more foodservice visits than its share would suggest. Millennials and Gen X also over-index. Baby Boomers, by contrast, account for 29% of the population but record a visit index of just 60.
Branded restaurants capture much of the younger generations’ spending. Branded concepts account for 29% of commercial restaurant spend overall, rising to 40% among Generation Alpha and 35% among both Gen Z and Millennials, compared with 24% for Gen X and 16% for Baby Boomers. Circana links this to younger consumers’ emphasis on immediacy, personalisation and digital ordering.
Generation Alpha’s delivery share is already 1.3 times the population average and seven times that of Baby Boomers.
Gen Z’s health-conscious routines
Gen Z is putting health intentions into practice. Twelve per cent practise intermittent fasting, compared with 7% of the overall population, while 24% focus on high-protein consumption and 20% prioritise organic or natural products. A further 13% report avoiding coffee.
Circana advises operators to look beyond adding individual better-for-you items and to consider how the broader offer fits changing meal routines.
Millennials drive solo dining
Nearly 60% of foodservice occasions now involve one or two people, and solo dining accounts for a third of all main-meal visits. Contrary to assumptions, Millennials lead this trend and spend around 70% more per visit when dining alone than when eating in a group.
Menus have not fully adapted. Solo diners are markedly less likely to order fish, seafood, pasta or noodles than the same consumers dining in groups, suggesting room for portion and format innovation.
Value is about more than price
Gen X illustrates a more nuanced view of value. Although 69% cite the cost of living as a concern, price ranks third in restaurant choice at 27%, behind product offer (35%) and convenience (33%).
Baby Boomers: an untapped opportunity
Boomers’ lower frequency is concentrated in the evening, when tiredness encourages earlier nights. When they do eat out, however, they disproportionately favour long lunches and dinners lasting more than two hours. Branded concepts capture only 16.1% of their spend, pointing to significant headroom for operators willing to design slower, more sociable occasions.
Implications for operators
- Digital ordering, delivery and personalisation are essential to winning younger consumers.
- Menus should accommodate protein-focused and time-restricted eating patterns.
- Solo-friendly portions and formats represent an under-served revenue opportunity.
- Daytime, long-stay occasions could unlock growth among older consumers.
As Uranga concluded, many behaviours that are generational today are likely to spread more widely over time, and operators that recognise them early will be best placed to grow.
Sources & Credits
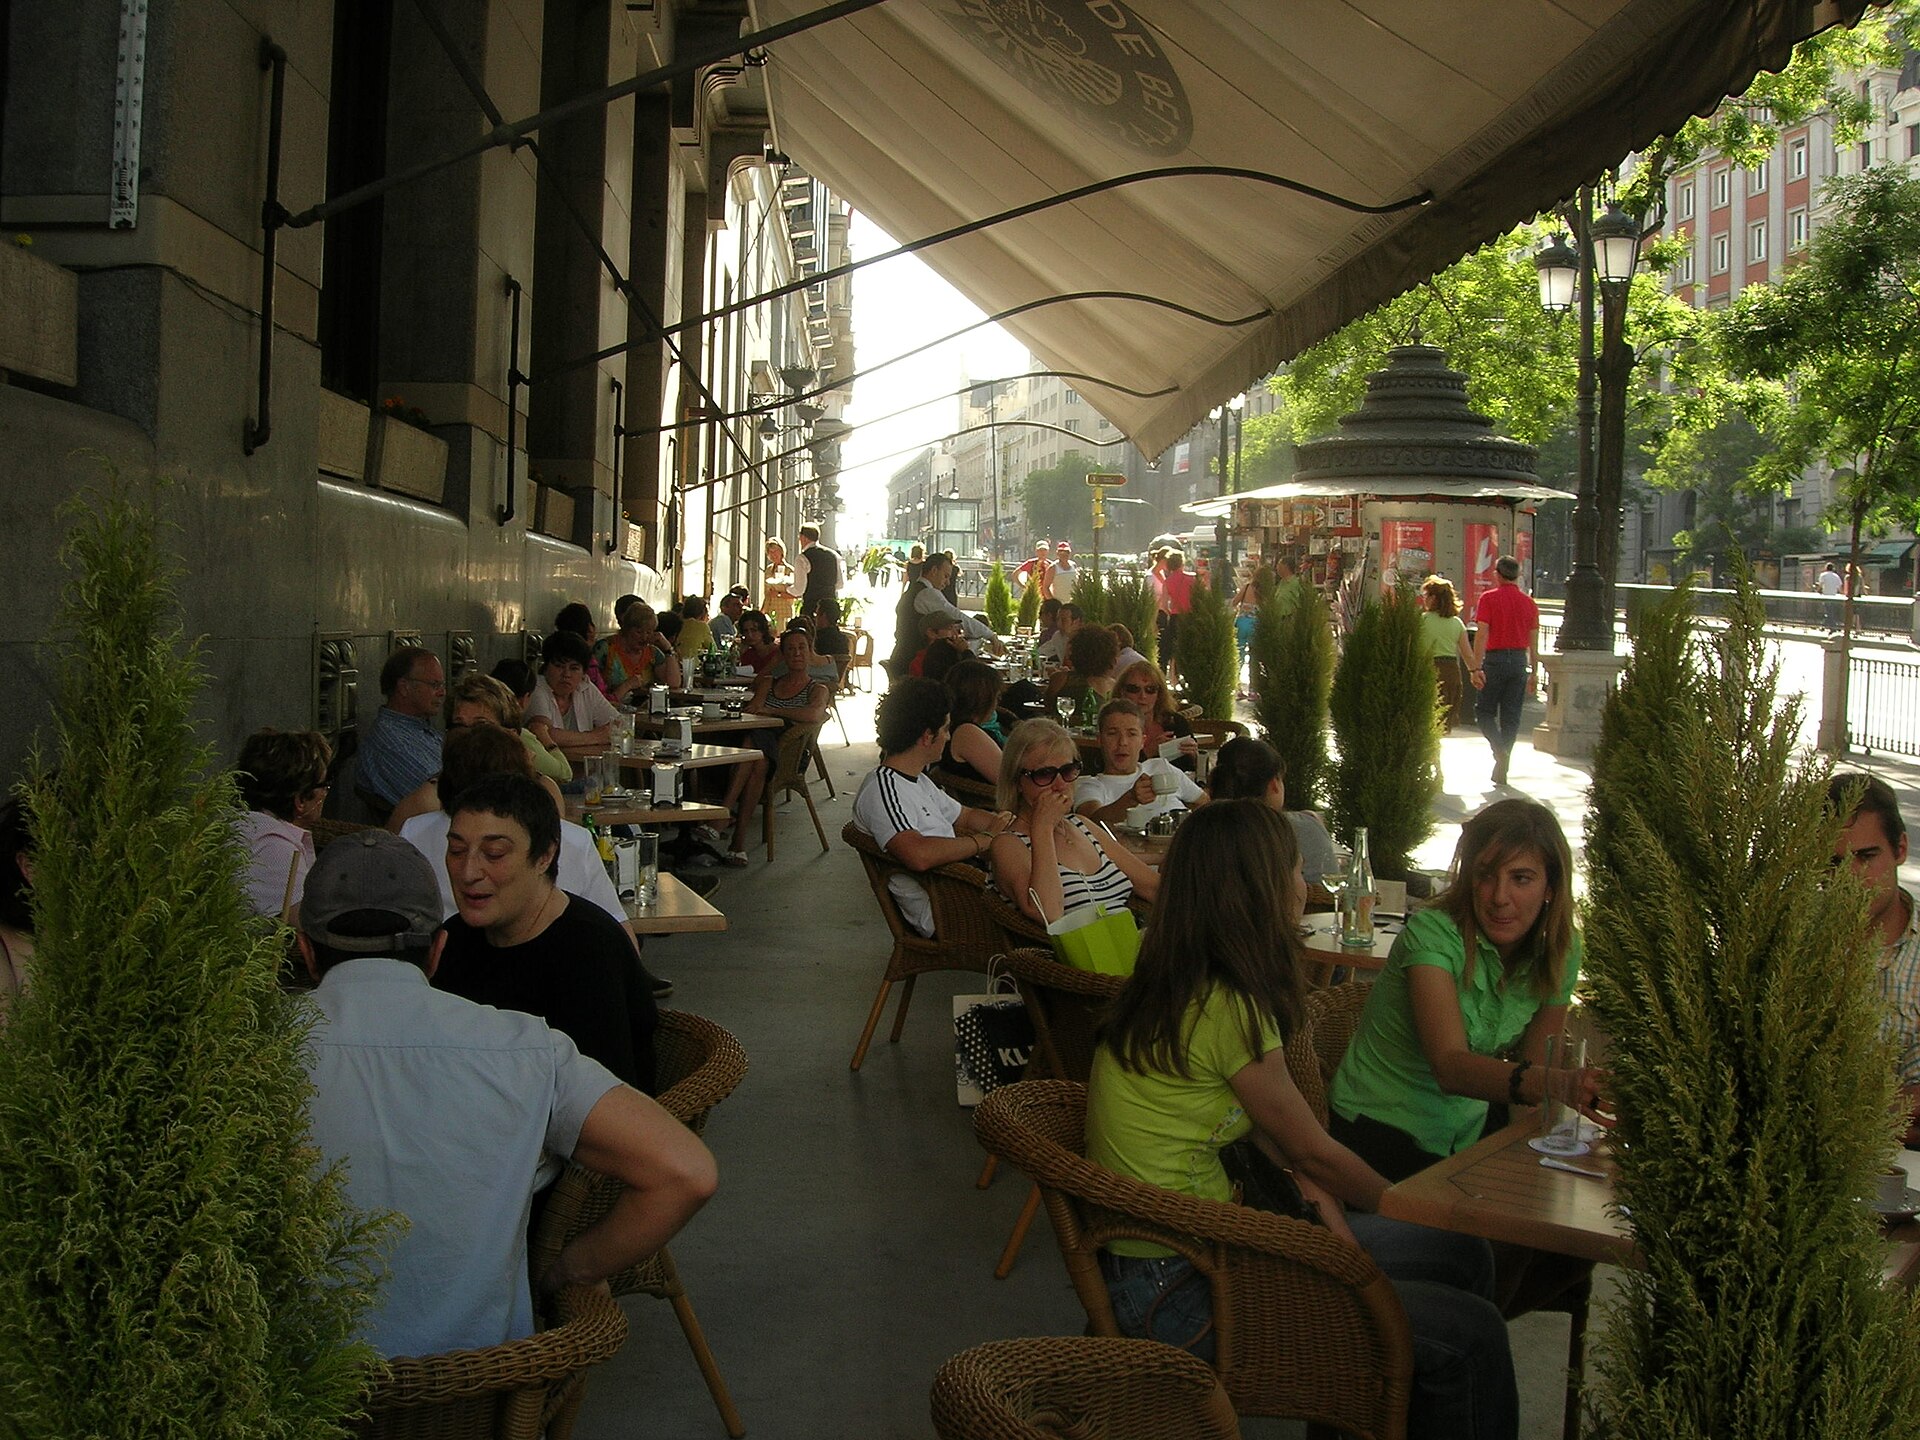
Featured image: Madrid Cafe de Bellas Artes by Gideon, via Wikimedia Commons (CC BY 2.0).
Reporting is based on the publicly available sources listed above and has been independently written by Food Tech Insider.